App Builder for Insurance Companies: Complete Guide
2 hours agoPUBLISHED INAi Development
 ali
 2026-10-06 12:57:00
 0
A broker emails a policy change on Tuesday. The service rep forwards it to underwriting. Underwriting replies to the rep, not the broker. By Friday the broker calls, annoyed. Nobody can say who last touched it. Sound familiar?
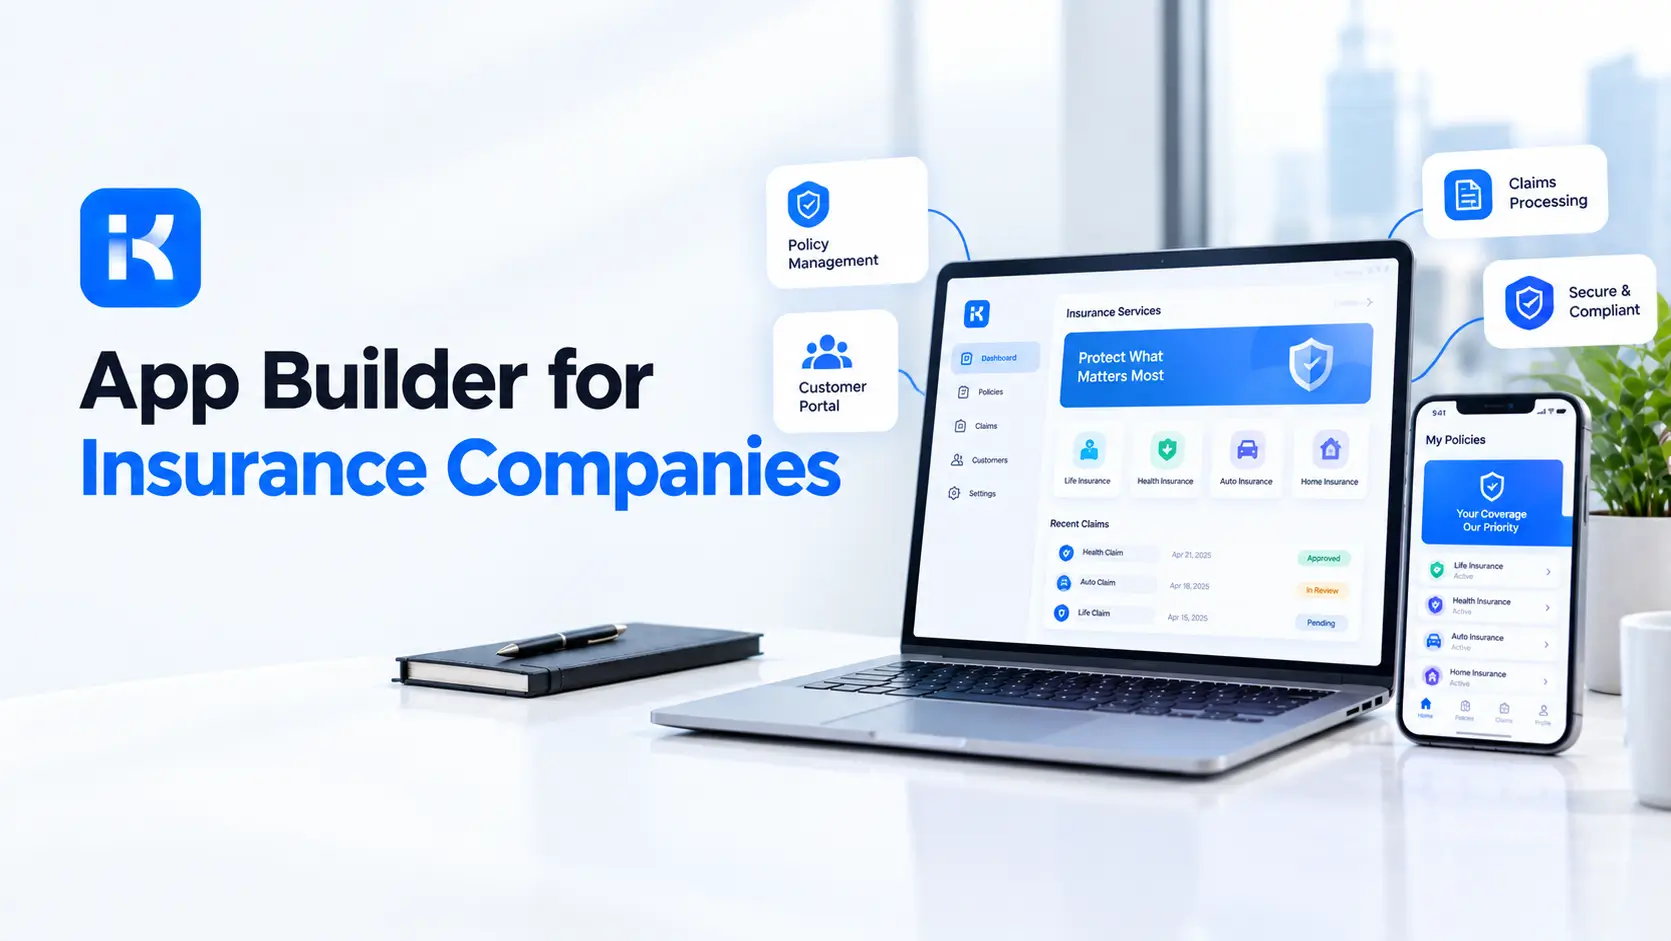
Core insurance systems do their job well. The trouble is the gaps between them, where work lives in inboxes and spreadsheets. An app builder for insurance companies fills those gaps. Below we cover where it helps, what to check before you pick one, and where it does not fit. If you want to see it on one of your own messy processes, you can book a KodeFlex demo at any point.
What is an app builder for insurance companies?
It is software that turns a plain description of a process into a working internal app. You type something like "brokers submit a change request, service checks it, underwriting approves anything above a set limit." The tool builds the forms, the approval steps and the screens. Then you adjust.
Developers are still needed for the heavy stuff. But the small, very specific apps that a claims or agency team wants no longer sit in an IT queue for half a year. Most of those requests are about people handing work to each other. Who submits. Who reviews. Who gets told.
Worth saying plainly: this is the layer around your policy admin and claims systems. It does not replace them.
Where insurance teams use internal apps
Start with work that bounces between people or departments. That is where things get lost.
|
Use case |
What the app does |
Who touches it |
|---|---|---|
|
Claims intake and tracking |
Captures the first notice of loss in a structured form, scores urgency, routes to an adjuster, shows status. |
Claims intake, adjuster, supervisor |
|
Policy change requests |
Request comes in with a reason and documents. Rules route it by type and amount. |
Service team, underwriting, agent |
|
Agent onboarding |
Checklist for documents, licence checks, training and sign-offs, with an owner for each step. |
Agency manager, compliance, IT |
|
Underwriting referrals |
Cases outside an underwriter's authority go up to a senior reviewer with the file attached. |
Underwriter, senior reviewer |
|
Audit trails |
A clear record of who did what and when, on every request. |
Compliance, internal audit |
Claims intake and tracking
Claims is where speed matters most. A policyholder wants to know what happens next. Assured's guide to the first notice of loss process describes five stages: capture the incident, validate the data, triage, route, and follow up with the customer. Each stage is a place where an internal app can give a request an owner and a status.
Structured intake helps a lot. The same guide says collecting dates, locations, parties and circumstances as clean data cuts the clarifying back and forth for adjusters. A form with required fields does that. A free text email does not.
Policy change requests
Address changes are easy. Coverage changes are not. A good app sorts them. Simple ones go straight through. Anything above a set limit goes to underwriting, with a reason attached. The agent can see where it is without calling anyone.
Agent onboarding
A new agent needs contracts, ID checks, licence verification, system access and training. Each step belongs to a different person. In email it is chaos. In an app it is a checklist where every step has a name next to it and a due date.
Underwriting referrals
Every underwriter has a limit. Past it, the case needs a second opinion. A referral app packages the file, sends it to the right senior person and records the decision with a comment. No more "did you see my email?"
Audit trails
Audits are painful when the story is scattered across inboxes. If every request moves through one app, the history sits in one place. Honestly, that alone justifies a lot of these projects. But check the detail with your vendor, because audit logging is something you should see working, not assume.
What to look for in an app builder for insurance companies
Plenty of tools promise this. A few things separate the useful ones from the demos.
-
Approval flows that handle real rules. Amount limits, branches, second approvers. Insurance approvals are rarely one step.
-
Roles and permissions. A claims handler should not see underwriting notes by default. Ask how access is set up.
-
Editable output. If AI builds the first version, you must be able to change it without starting over.
-
Versioning. Rules change when products change. You need to roll back when a tweak goes wrong.
-
Deployment choice. Insurers handle sensitive personal and financial data. Ask whether the app can run on your own servers.
-
Honest limits. A vendor that tells you what it does not do is easier to trust.
Why private deployment matters for insurers
Claims files hold medical details, addresses, bank data and photos of people's homes. Many insurers do not want that on a shared cloud they cannot see into. Some are told by their own policies to keep it close.
So ask early where the app runs and where the data sits. It is a boring question. It is also the one that kills projects late, when security finally reads the proposal. KodeFlex says it supports private deployment. More on that below.
One caution. A deployment option is not a compliance answer. Rules differ by country, line of business and regulator. Talk to your compliance and legal people before you load real policyholder data into anything.
How KodeFlex fits
KodeFlex is an AI development platform from EasySoft INC. According to the KodeFlex product page, you describe a business need in natural language and it generates a runnable application, with frontend, backend and approval flows included. You then refine forms, actions and workflows visually.
|
Insurance need |
What the KodeFlex pages describe |
|---|---|
|
A first version fast |
One-prompt generation of the app, with editable structured configuration. |
|
Approval rules |
Workflow orchestration with approval paths, routing logic, business rules and branches. |
|
Changes over time |
Version control, live preview, one-click release and deployment. |
|
Many teams or regions |
Multiple instances from one app, with one-click upgrades, and the option to enable or suspend an instance. |
|
Data control |
Private deployment option, so data does not have to leave your own environment. |
The KodeFlex home page lists internal business process automation among its core uses. On cost, the pricing page shows lifetime licenses from $1,499 (Team, 50 users, 20 apps) and annual licenses from $3,699. Plans change, so check the page before you set a budget.
Where an app builder does not fit
Let's be straight. KodeFlex is built for internal business apps. It is not a core policy administration system. It does not rate premiums, issue policies, run billing or hold the policy of record. Keep your core system for that.
It is also not meant for consumer mobile apps or graphics-heavy products. So a policyholder app in the App Store is a different project.
And some things we cannot claim from the public pages. The KodeFlex site does not detail role-based permissions, audit logging or specific integrations with claims or policy systems. If those matter to you, and for insurers they usually do, ask for them on a demo. Do not assume. Nothing in this article is regulatory or legal advice, and KodeFlex does not claim any certification on its public pages.
An illustration: a referral app for underwriting
Picture a mid-sized insurer where underwriters email risky cases to a senior reviewer. Replies get buried. (This is an illustration, not a case study.)
-
Describe it. The underwriting lead writes a short brief. Underwriters submit a case with the file. A senior reviewer approves, declines or asks for more.
-
Refine it. Cases above a set sum need two reviewers. That is one rule in the workflow editor.
-
Test it. Three underwriters use it for two weeks. They find there is no field for the broker's name. It gets added in minutes.
-
Roll out. The wider team joins. Each referral has an owner, a status and a decision comment.
What changes? The senior reviewer opens one list instead of digging through email. Underwriters stop chasing. Brokers get an answer, not silence.
Checklist: before you build your first insurance app
-
Pick one process with daily friction. Referrals and change requests are safe starts.
-
Write down who submits, who reviews and who gets told.
-
List the rules, including limits and exceptions.
-
Ask compliance what the app may and may not hold.
-
Decide who sees what, by team and by role.
-
Decide where the app should run and where the data should sit.
-
Check how it connects to your claims or policy system, if it must.
-
Pilot with one small team for two weeks. Then widen it.
Ready to test it on your own workflow? Book a KodeFlex demo and bring your messiest process. You can also download KodeFlex to try it yourself.
Frequently asked questions
What is an app builder for insurance companies?
It is a tool that turns a plain description of a process into a working internal app. Insurance teams use it for claims tracking, policy change requests, agent onboarding and underwriting referrals. It handles the work around your core systems, not the core systems themselves.
Can it replace our policy administration system?
No. A policy admin system rates, issues and bills. KodeFlex is for internal business apps, so it sits next to that system and not in place of it.
Do we need developers to use one?
Not for most team level apps. Someone who knows the process can describe it and adjust the result. For links to other systems you may still want technical help, so ask about that early.
Is it compliant with insurance regulations?
That is a question for your compliance team, and we cannot answer it for you. The KodeFlex site does not claim any certification. It does mention private deployment, which may help with data control. Check your own requirements first.
Why does private deployment matter?
Claims and policy files hold sensitive personal data. Private deployment means the data stays in your own environment, not on a shared cloud. KodeFlex lists it as an option.
How long does it take to build an insurance app?
The KodeFlex site says one prompt can produce a runnable app within minutes. A real rollout takes longer, because people need to test it and you will change things. Plan for a pilot of a couple of weeks.
How much does KodeFlex cost?
The pricing page lists lifetime licenses from $1,499 for the Team edition (50 users and 20 apps), and annual licenses from $3,699. Plans can change, so check the page for current numbers.
|
Want to see an app builder for insurance companies on your own process? Bring one workflow that keeps getting stuck between teams. We will show you how it looks as a working app. Book a KodeFlex demo to see it live, or look at the product page first. |
Related Blogs
Business Process Automation: A Complete Guide